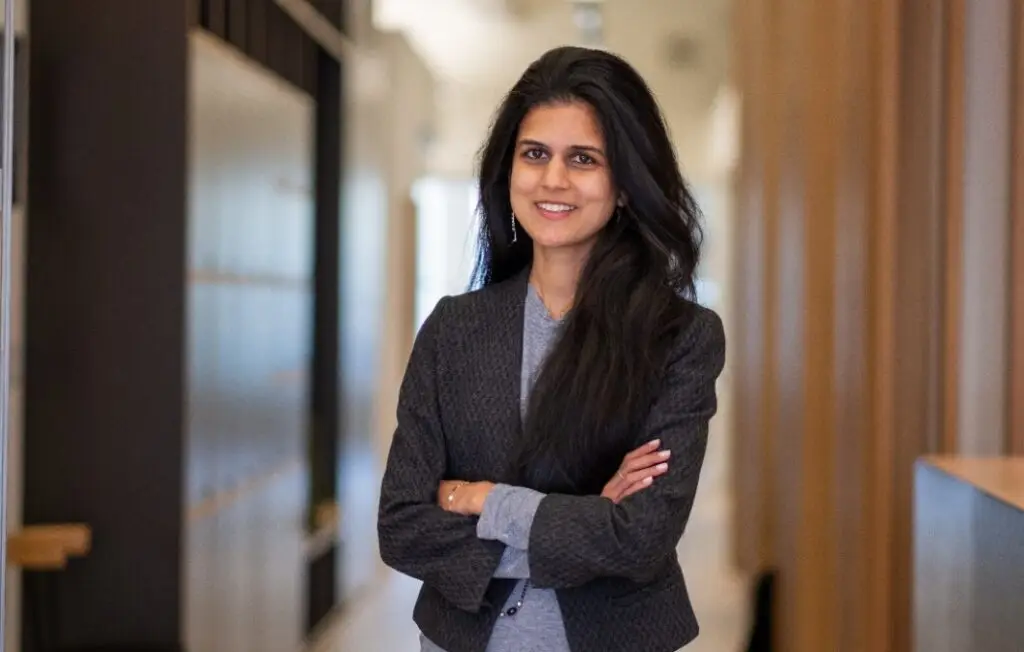
It can be difficult to distinguish between a high-spend business that is burning through cash on its way into the ground, and one that will eventually be rewarded with even greater growth. Diya Sagar is toeing that narrow line as the CFO of AWA (Artists, Writers & Artisans) based in New York City.
“It isn’t always obvious whether particular investments are going to pay off, especially if they require months or longer to deliver results,” she says in an interview with CFO Leadership. “So the question I ask myself is: Does this bet have a relatively high likelihood of being worth the reward, and can we pursue it without putting the company’s future at risk?”
Sagar shares her insights from growing an early-stage, creative endeavor, including attracting investors and keeping them on board amid unpredictable performance.
How do you keep the board and investors on side when the business isn’t performing to plan?
Communicate—early, clearly and honestly. When a business isn’t performing in line with forecasts, it is natural for the CFO to go into defense mode. After all, that’s how the business will be presenting it to you: We missed budget, and here’s why, but it’s not our fault. As CFO though, you have a fiduciary duty to the company and its shareholders, which not only includes reporting financial results, but providing the true context.
As soon as you realize the business is missing its numbers, identify why and what can be done about it. What needs to happen to bring the financials back on track, or does this require a strategic change? Next, steer the business into taking those actions. If resources need to be allocated elsewhere, begin that process. And then, show your board and investors that you have a plan to protect their capital.
I’ve found that by communicating openly, I can prevent a short-term miss from turning into long-term underperformance. Usually, our board and investors will also provide advice to help us recalibrate, which is how I know that they’re still on side.
How do you manage a cash-burning business so that it is burning cash for the “right” reasons?
Cash-burning businesses can have extremely different outcomes. On one side of the spectrum, a company that is consistently generating losses may end up burning through its coffers and eventually run itself out of business. On the other side of the spectrum, some of the most highly valued businesses today are burning billions of dollars a year and are still being rewarded with more funding. Herein lies the dichotomy.
As CFO of an early-stage business, I need to ensure that any cash we burn is being invested for growth and that over time will increase the equity value of the company. In practice, what this means is that any spend—on people, product, technology—is going towards building a business that will ultimately be worth multiples more than the dollars we are investing today.
I’ll admit though, it isn’t always obvious whether particular investments are going to pay off, especially if they require months or longer to deliver results. So the question I ask myself is: Does this bet have a relatively high likelihood of being worth the reward, and can we pursue it without putting the company’s future at risk? If the answer is yes, I can proceed believing that we’re burning cash for the “right” rather than the “wrong” reasons.
Investors like businesses with sticky, recurring revenue. How do you attract investors if your business doesn’t have that?
AWA is a media and entertainment business. Like other companies in our space, we have a hit-driven business model, which means that revenue is lumpy and unpredictable. Unlike the recurring revenues of SaaS and stickiness that comes with AI revenue models, we have limited future visibility over when exactly our projects will become “hits” in Hollywood. So attracting investors actually ends up being a self-selecting process.
What I mean by that is the kinds of investors who understand the ups and downs of our financial profile and whose capital base can match our long-term time horizon, are those who are drawn to invest in a business like this. Pools of capital certainly exist, typically amongst strategics and those with long-term patient capital.
Because of that, we have a shareholder group that is very supportive of the company, and I’d encourage all CFOs to seek investors who are similarly aligned not only on the end goals for the business, but what it will take to get there.
Can CFOs ever be seen as the “nice guy or gal”?
As much as I hope so, that’s probably a stretch! Although there are times when being a bad cop is necessary, as CFOs we tend to get stuck with that being the only way we’re perceived in organizations. My own approach is to try to say yes before I say no—when a team or part of the company makes a case for needing more resources, or when there is an opportunity they really believe in that requires investment, I want to make it possible within the confines of the business.
Of course, that has to come after an assessment of trade-offs, and often times an idea may need to be re-worked to make it commercially viable. Trying to get to yes makes capital allocation decisions much harder because it requires you to scrutinize returns harder, but pushing yourself to see opportunity where you may not have seen it before may actually be the “nicer” way to go.